Insurance Companies Must Deal In A Bonafide & Fair Manner ;
Insurance Companies Must Deal In A Bonafide & Fair Manner ; Should Not Just Care For Its Own Profits : Supreme Court
|
The Supreme Court observed that an insurance is expected to deal with the insured in a bonafide and fair manner and should not just care for and cater to its own profits.
It is the duty of the insurance company to disclose all material facts within their knowledge since the obligation of good faith applies to both equally, the bench of Justices AS Bopanna and Sanjay Kumar observed.
In this case, the complainant, who had undertaken prawn cultivation in an extent of 100 acres, had obtained insurance coverage from an Insurance Company. There was a major outbreak of a bacterial disease called ‘White Spot Disease’ along the east coast of Andhra Pradesh, which led to mass mortality of prawns. He invoked the policy but the Insurance company repudiated the appellant’s claim in its entirety, on the ground that there was a breach by the complainant of the policy conditions, inasmuch as records were not maintained properly and accurately. NCDRC, disposing his complaint, assessed his total loss as ₹30,69,486.80. Dissatisfied with this order, the complainant approached the Apex Court.
At the outset, the court noted that that uberrima fides, i.e., good faith, is the requirement in a contract of insurance.
“It it is the fundamental principle of insurance law that utmost good faith must be observed by the contracting parties; that good faith forbids either party from non-disclosure of the facts which the party knows; and that the insured has a duty to disclose and similarly it is the duty of the insurance company to disclose all material facts within their knowledge since the obligation of good faith applies to both equally. This obligation and duty would rest on both parties not only at the inception of the contract of insurance but throughout its existence and even thereafter.”
The bench noted that the insurance company baldly brushed aside the Death Certificate dated 01.05.1995 furnished by the officials of the State Fisheries Department at Visakhapatnam.
“Merely because the contents thereof were not to its liking, the insurance company could not have ignored the same and swept it under the carpet. More so, as such certification was being made by impartial and independent bodies of significant stature and that, perhaps, was precisely the reason why the insurance company had attached such importance to it in its norms. In any event, it is not open to an insurance company to ignore or fail to act upon a certificate or document that it had itself called for from independent and impartial authorities, subject to just exceptions, merely because it is averse to it or to its detriment. Having undertaken to indemnify an insured against possible loss in specified situations, an insurance company is expected to make good on its promise in a bonafide and fair manner and not just care for and cater to its own profits
Allowing the appeal, the court ordered that a sum of ₹45,18,263.20 shall be remitted by the insurance company to the appellant, with simple interest thereon @ 10% from the date of the complaint till the date of realization, within six weeks.
Isnar Aqua Farms vs United India Insurance Co. Ltd
Insurance Law – Uberrima fides, i.e., good faith, is the requirement in a contract of insurance – It is not open to an insurance company to ignore or fail to act upon a certificate or document that it had itself called for from independent and impartial authorities, subject to just exceptions, merely because it is averse to it or to its detriment. Having undertaken to indemnify an insured against possible loss in specified situations, an insurance company is expected to make good on its promise in a bonafide and fair manner and not just care for and cater to its own profit – It is the fundamental principle of insurance law that utmost good faith must be observed by the contracting parties; that good faith forbids either party from non-disclosure of the facts which the party knows; and that the insured has a duty to disclose and similarly it is the duty of the insurance company to disclose all material facts within their knowledge since the obligation of good faith applies to both equally. This obligation and duty would rest on both parties not only at the inception of the contract of insurance but throughout its existence and even thereafter. (Para 12-13)
Post Categories
Featured Posts
Latest Posts
Latest Posts
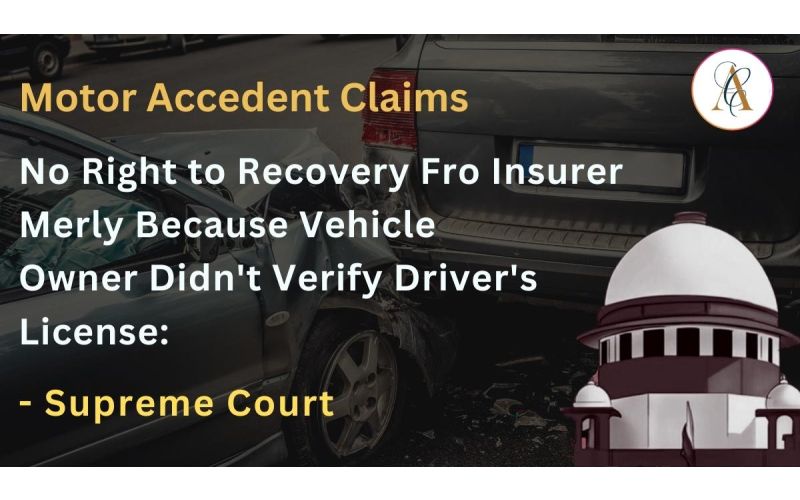
Motor Accident Claims | No Right To Recovery For Insurer Merely Because Vehicle Owner Didn't Verify Driver's License : Supreme Court
The Supreme Court on Monday (30th October) held that an insurance company cannot claim that it is not liable to pay compensation in a motor vehicle accident claim just because the vehicle owner did not verify the genuineness of the ...
S.138 NI Act | Proceedings For Cheque Dishonour Need To Be Quashed Once Complainant Signs Deed Accepting Amount In Final Settlement : Supreme Court
In a Criminal Appeal arising out of proceedings under Section 138 of the Negotiable Instruments Act, 1881, the Supreme Court has ruled that once the settlement has been arrived at and the complainant has signed the deed, the proceedings under ...
ADR in Workplace Conflicts: A Guide for Employers and Employees
Workplace conflicts are inevitable. Whether stemming from miscommunication, differences in expectations, or interpersonal issues, they can disrupt the professional environment and affect productivity. For both employers and employees, finding a way to resolve these conflicts quickly, fairly, and cost-effectively is ...
Lessons Every Young Lawyer Should Learn Early
The legal profession is more than a career—it is a lifelong commitment to justice, responsibility, and public service. Every advocate begins their journey with ambition, knowledge, and the desire to make a meaningful impact. However, success in the legal profession ...
🤝 Mediation vs. Arbitration: Choosing the Right Path in ADR ⚖️
Alternative Dispute Resolution (ADR) has become an increasingly popular method for resolving disputes outside of traditional court litigation. Among the various ADR methods, mediation and arbitration stand out as two of the most commonly used approaches. While both aim to ...
An Exegesis On Criminal Offences: A Legal Discourse From The Pinnacle Of The Indian Judiciary
Index: Introduction Understanding Criminal Offences 2.1 Petty Offences 2.2 Cognizable Offences 2.3 Non-Cognizable Offences Consequences of Criminal Offences 3.1 Legal Consequences 3.2 Social and Personal Impact 3.3 Societal Costs Conclusion———————————— Introduction: Criminal offenses encapsulate acts that transgress established laws and regulations, warranting punitive measures imposed ...
Speak With Our
Get a Appointment